Digital Economy & Fintech
Africa Digital Payments Outlook 2026: Fintech Adoption, Payment Infrastructure and Business
Explore Africa’s digital payments landscape in 2026, including mobile money, fintech platforms, merchant payments, cross-border transactions, payment infrastructure, and financial inclusion. This business intelligence overview examines key market drivers, infrastructure challenges, regulatory considerations, and potential opportunities for fintech companies, investors, merchants, and service providers across selected African markets.
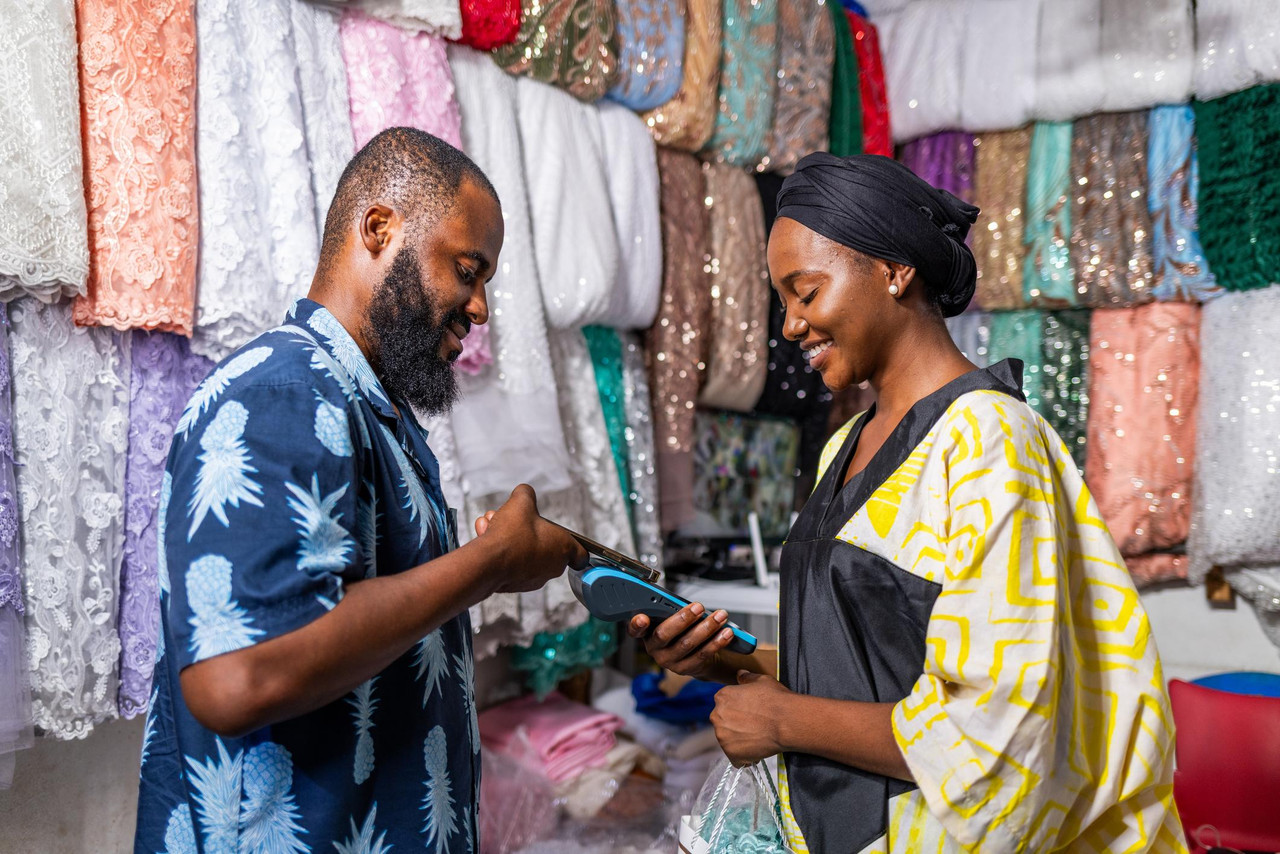
Digital payments are transforming how consumers, merchants, businesses, and institutions transfer money and conduct transactions across Africa. Mobile money, digital banking, payment gateways, merchant acceptance tools, and fintech platforms are creating new ways to serve customers and manage business operations.
However, Africa's digital payments market is diverse. Adoption, infrastructure, regulation, customer behaviour, and competition differ considerably between countries. Businesses seeking opportunities need to understand local market conditions rather than treating the continent as a single, uniform payments ecosystem.
- Mobile Money and Digital Financial Services
Mobile money remains an important part of digital financial services in several African markets, particularly where mobile-based transactions provide convenient alternatives to traditional banking.
Potential business opportunities include merchant payment acceptance, digital wallets, agent networks, payment integrations, business transaction tools, and services that help small enterprises manage collections and disbursements.
Commercial success depends on customer trust, transaction reliability, pricing, accessibility, fraud prevention, and the ability to address a clearly defined customer need.
- Merchant Payments and Business Digitisation
Small and medium-sized businesses increasingly need practical ways to accept electronic payments, reconcile transactions, track sales, and manage cash flow.
Payment service providers can investigate opportunities in point-of-sale solutions, payment links, online checkout, recurring billing, invoicing, transaction reporting, and integrations with accounting or inventory systems.
For merchants, the value of a payment solution extends beyond accepting money. Ease of use, settlement speed, transaction fees, customer support, and reliable records can influence adoption and retention.
- Cross-Border Payments and Regional Trade
Cross-border payments are important for businesses involved in imports, exports, international services, remittances, and regional trade. Traditional transfer processes can involve multiple intermediaries, foreign-exchange costs, compliance requirements, and settlement delays.
Potential opportunities include business payment platforms, remittance services, foreign-exchange transparency tools, payment orchestration, and technology that simplifies collections across supported markets.
Companies entering this segment must assess licensing requirements, currency conversion, settlement arrangements, sanctions screening, anti-money-laundering obligations, and the availability of reliable banking or payment partners.
- African Markets to Assess
Nigeria: Research opportunities in merchant payments, online checkout, payment infrastructure, business collections, digital banking, and fintech integrations. Market assessments should examine competition, transaction reliability, customer acquisition costs, regulatory requirements, and the needs of small businesses.
Kenya: Investigate mobile money integrations, merchant acceptance, digital financial services, business payments, and solutions connecting established payment channels with enterprise systems. Research should distinguish between existing customer demand and unmet needs that a new service could realistically address.
Ghana: Assess digital merchant payments, mobile money-enabled commerce, online payments, business transaction management, and payment solutions for smaller enterprises. Local adoption patterns, pricing, compliance, and merchant requirements should guide market entry decisions.
South Africa: Examine digital banking, e-commerce payments, payment gateways, merchant services, and enterprise payment infrastructure. Competitive positioning, integration capabilities, consumer protection, fraud controls, and regulatory obligations are important considerations.
These markets provide starting points for comparative research, not a ranking of investment returns or confirmation that any particular opportunity is commercially viable.
- Infrastructure, Trust and Regulatory Challenges
Digital payment providers face challenges involving internet access, service interruptions, fraud, cybersecurity, interoperability, transaction disputes, and customer confidence.
Regulation is another critical factor. Licensing, data protection, consumer safeguards, payment-system rules, and anti-money-laundering requirements vary across jurisdictions and business models.
Before entering a market, companies should verify current requirements with the relevant financial regulator and qualified local advisers. They should also assess operational resilience, complaint handling, fraud monitoring, data security, and the reliability of settlement partners.
- How Business Intelligence Supports Fintech Decisions
Digital payments markets can be difficult to evaluate because information is spread across regulatory publications, company announcements, industry reports, payment-provider documentation, and local market evidence.
Structured business intelligence can help organisations compare competitors, assess target customer segments, map payment providers, investigate market-entry conditions, evaluate distribution channels, and identify gaps in available services.
Grow Africa Business Intelligence supports market research, competitive intelligence, opportunity mapping, and decision-ready reporting to help businesses investigate markets and prioritise further commercial validation.
Conclusion
Africa's digital payments ecosystem offers potential opportunities across mobile money, merchant services, e-commerce, cross-border transactions, and business payment infrastructure. Success depends on understanding local customer needs, regulatory requirements, competitive dynamics, operating costs, and the reliability of the underlying payment system.
Grow Africa Business Intelligence helps businesses turn market information into actionable intelligence for better-informed market-entry, partnership, and growth decisions.
Research note: This article provides a strategic market overview and does not constitute financial, legal, or investment advice. It does not verify specific investment offers, payment-provider performance, market shares, or guaranteed returns. Confirm current market statistics, licensing conditions, regulatory guidance, and provider capabilities through authoritative sources before making commercial decisions.